What Is a Payday Loans Direct Lender?
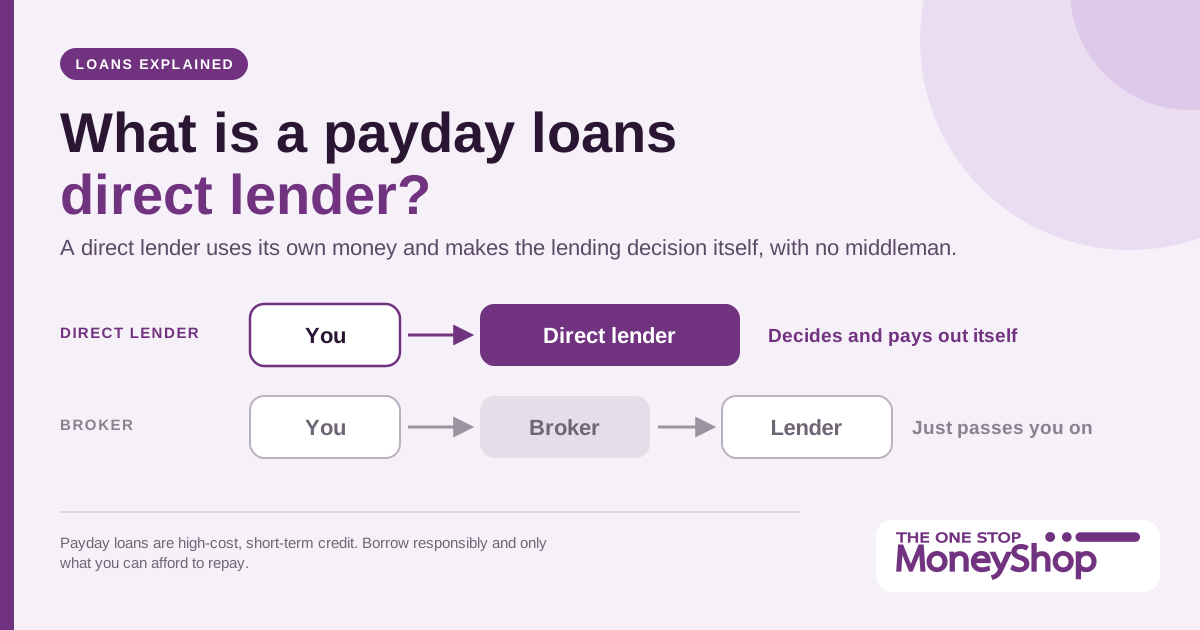
A payday loans direct lender is a company that assesses your application, makes the lending decision and pays the money into your bank account itself, without passing your details to anyone else. You deal with the same company from the moment you apply until your final repayment, and the lender’s name is on your credit agreement.
This is different from a credit broker, which collects your details and passes them on to one or more lenders. Brokers can be useful for comparing options, but using a direct lender means fewer companies see your personal information, you know exactly who you’re borrowing from, and you usually get a quicker answer.
The One Stop Money Shop has been a direct lender since 2005. In this guide, we explain how direct lenders work, what a payday loan from a direct lender costs, who can apply, and how to make sure the company you’re dealing with is genuine.
What is the Difference Between a Broker and a Payday Loans Direct Lender?
The difference between a direct lender and a broker is that direct lender lends you its own money and makes the decision itself, while a broker introduces you to other companies that might lend to you.
When you apply through a broker, your details may be shared with several lenders until one of them accepts you. Some brokers charge a fee, and you may receive calls, texts or emails from companies you’ve never heard of. A direct lender keeps your application in-house, so you only hear from the company you applied to.
| Payday loans direct lender | Credit broker | |
|---|---|---|
| Who makes the decision? | The lender itself | The lenders it passes your details to |
| Who pays out the money? | The lender, straight to your bank account | A third-party lender |
| How many companies see your details? | One | Potentially several |
| Can it charge a fee for applying? | No | Some brokers charge fees, which must be clearly disclosed |
| Who do you repay? | The same company you applied to | The lender that accepted you |
| Who handles complaints? | The lender | Usually the lender, though the broker is responsible for its own service |
| Typical speed | Often a same-day decision | Can be fast, but depends on which lender picks up the application |
A broker can still be useful if you want to see offers from several lenders in one place. But if you want a clear, direct relationship and to know exactly who has your information, applying with a direct lender is usually simpler.
How Much Does a Loan Cost With a Payday Loans Direct Lender?
The cost of a loan from a payday loans direct lender depends on how much you borrow and how long you take to repay, but by law you can never pay back more than double the amount you borrowed. Since 2015, the FCA has applied a price cap to high-cost short-term credit, including payday loans:
- Interest and fees can’t exceed 0.8% of the amount borrowed per day
- Default fees are capped at £15 if you miss a payment
- The total cost of the loan, including all interest and charges, can never exceed 100% of what you borrowed
That means if you borrow £500, the most you could ever repay in total, even if things go wrong, is £1,000.
Repayment example
At The One Stop Money Shop, loans range from £400 to £2,500 and are repaid in equal monthly instalments, rather than one lump sum on payday. Here’s what some typical loans could cost:
| Amount borrowed | Term | Monthly repayment | Total repayable | Total cost of borrowing | Representative APR |
|---|---|---|---|---|---|
| £400 | 6 months | £97.68 | £586.10 | £186.10 | 295.6% |
| £500 | 12 months | £81.25 | £975.00 | £475.00 | 295.6% |
| £600 | 12 months | £95.00 | £1,140.00 | £540.00 | 272.6% |
| £1,000 | 12 months | £162.51 | £1,950.08 | £950.08 | 295.6% |
Illustrative examples. The £500 and £600 examples are The One Stop Money Shop’s published representative examples. Your actual rate and repayments will be shown before you sign your agreement and will depend on your circumstances. See why you may not get the rate advertised for a loan.
Payday loans are an expensive way to borrow, and the APR looks very high because it’s calculated as if the loan ran for a full year with interest compounding. You can read more about why payday loans are so expensive. Repaying early can reduce what you pay, because you’re only charged interest for the time you’ve had the money.
What is the Eligibility for a Payday Loans Direct Lender?
To be eligible for a loan from a payday loans direct lender, you’ll usually need to be a UK resident over 18 with a regular income, a UK bank account and enough money left each month to afford the repayments. Each lender sets its own criteria, and some are stricter than the legal minimum.
To apply with The One Stop Money Shop, you’ll need to:
- Be aged 22 or over
- Be a UK resident
- Have been employed for at least six months
- Have a valid UK bank account with a debit card
- Have a UK mobile number and email address
- Be able to afford the monthly repayments after your essential bills
Every FCA-authorised lender must also carry out an affordability assessment. This means looking at your income, outgoings and existing credit commitments to make sure the loan won’t cause you financial difficulty. If the repayments wouldn’t be affordable, a responsible lender should decline your application, even if you meet the other criteria.
Can I Get a Loan From a Payday Loans Direct Lender With Bad Credit?
Yes, you can get a loan from a payday loans direct lender with bad credit, as many direct lenders focus on whether you can afford the repayments now rather than on mistakes you’ve made in the past. A low credit score, missed payments or even a County Court Judgment (CCJ) won’t automatically rule you out.
What lenders mainly want to see is a stable income and a budget that leaves room for repayments. If your circumstances have improved since your credit problems, for example if you’ve been in a steady job for a while or cleared old debts, that will work in your favour.
At The One Stop Money Shop, we consider applicants with poor credit histories and CCJ loans. Find out more about our bad credit loans.
A few tips if your credit isn’t perfect:
- Only borrow what you need and can comfortably repay
- Check your credit report for errors before applying
- Avoid making lots of applications in a short time, as multiple hard searches can lower your score
- Be honest about your income and outgoings on your application
Can I Get a Payday Loan From a Direct Lender With No Credit Checks?
No, you can’t get a payday loan from a genuine UK direct lender with no credit checks, because FCA rules require every authorised lender to assess your creditworthiness before lending. Any company advertising “no credit check” payday loans in the UK is either using misleading wording or isn’t operating legally.
What many lenders do offer is a soft search at the start, which lets them check whether you’re likely to be accepted without leaving a visible mark on your credit file. If you go ahead with a full application, a hard search is normally carried out before the loan is approved. This will show up on your credit report.
A lender that genuinely doesn’t check your credit or affordability is a red flag. It could be an unauthorised lender, sometimes called a loan shark, which isn’t bound by the FCA’s price cap or its rules on treating customers fairly.
How Do I Know a Company is a Payday Loans Direct Lender?
You can tell a company is a payday loans direct lender by checking its FCA authorisation on the Financial Services Register and reading the regulatory wording on its website, which should state that it’s a lender rather than a credit broker. Here’s what to look for:
1. Check the FCA Register – Search the company’s name or firm reference number on the FCA Financial Services Register. The entry will show whether the firm is authorised and which activities it’s permitted to carry out. A direct lender will be permitted to enter into regulated credit agreements as lender, while a broker will have permission for credit broking.
2. Read the website footer – All authorised firms must show their regulatory status on their website, usually in the footer. A direct lender will typically say something like “authorised and regulated by the Financial Conduct Authority” alongside its firm reference number. A broker will normally state that it is “a credit broker, not a lender”. For example, The One Stop Money Shop’s footer confirms that The One Stop Money Shop Ltd is authorised and regulated by the Financial Conduct Authority, registration number 713424.
3. Look at who’s named on the agreement – Before you sign, your credit agreement will name the lender. If it’s a different company from the one whose website you applied on, you’ve used a broker.
4. Watch for mentions of “partners” or “panels” – If a website says it will search “a panel of lenders” or share your details with “trusted partners”, it’s acting as a broker.
5. Check the company’s history – Genuine direct lenders usually have a registered office, a Companies House listing and a clear complaints procedure.
You can also read our guide on how to know a payday lender is legitimate.
How Do You Know a Payday Lender is Not a Scam?
You can tell a payday lender isn’t a scam if it’s listed on the FCA Register, never asks for money upfront, and gives you clear loan terms before you sign. Loan scams are common, and criminals often copy the names and branding of real lenders, so it pays to be careful.
Warning signs of a scam include:
- Upfront fees: Genuine lenders never ask you to pay an “admin”, “insurance” or “release” fee before you receive your loan
- Guaranteed approval: No legitimate lender can guarantee a loan without checking your circumstances
- Unusual payment methods: Requests to pay by bank transfer to a personal account, gift cards, vouchers or cryptocurrency
- Pressure tactics: Being told an offer will disappear unless you act within minutes
- Cold contact: Unexpected calls, texts or social media messages offering you a loan
- Contact details that don’t match: Phone numbers, emails or web addresses that differ from those on the FCA Register
If you’re unsure whether a lender is genuine, use the contact details listed on the FCA Register, not those given in the message or advert. If you think you’ve been targeted by a scam, report it to your bank straight away. For free, impartial guidance on borrowing and debt, you can visit MoneyHelper, which is backed by the government.
Why Use One Stop as Your Payday Loans Direct Lender?
You can use The One Stop Money Shop as your payday loans direct lender because we’ve been lending directly to UK customers since 2005, we’re authorised and regulated by the FCA, and we never pass your application on to other lenders.
- A genuine direct lender: We assess and fund every loan ourselves, so you always know who you’re dealing with
- FCA authorised: The One Stop Money Shop Ltd is authorised and regulated by the Financial Conduct Authority, registration number 713424
- Borrow £400 to £2,500: Choose an amount that suits your needs and affordability
- Spread the cost: Repay in equal monthly instalments over 6 to 24 months, rather than all at once
- Bad credit considered: We look at your current situation, and applicants with CCJs can still apply
- Fast decisions: Most applications are decided within one to two hours
- Same-day funding: Loans fully approved before 3:30pm are usually paid the same working day. Find out more about urgent same day loans
- No fees to apply: Applying is free
If you’d prefer to spread your repayments over a longer period, take a look at our instalment loans which can spread repayment over 6 to 24 months.
FAQs
Are payday loans from a direct lender cheaper than through a broker?
Not always, but using a direct lender means there’s no risk of paying a broker fee. The interest you pay is set by the lender in either case, and all payday lenders must stay within the FCA price cap. If you use a broker for something like a bigger personal loan or mortgage, the likelihood is that they will compare lots of lenders and rates and help you get the best terms, but there might be a broker fee involved.
How quickly will I receive my money for a direct lender?
You’ll usually receive your money on the same working day if your loan is fully approved before 3:30pm. Most decisions are made within one to two hours. Applications approved later in the day, or at weekends and on bank holidays, are normally paid on the next working day.
Will applying affect my credit score?
A full loan application will usually involve a hard credit search, which is recorded on your credit file and may affect your score for a short time. Some lenders use a soft search first to check your eligibility, which doesn’t affect your score.
Can I repay my loan early?
Yes, you have a legal right to repay a consumer credit agreement early, in full or in part. You’ll only pay interest up to the date you repay, so clearing your loan early can save you money.
Can I roll over or extend my payday loan?
FCA rules limit payday loan rollovers to a maximum of two. Whether a lender offers one at all depends on its policy. If you’re struggling to repay, it’s better to speak to your lender about a repayment plan than to extend the loan.
What happens if I can’t repay my payday loan?
If you miss a repayment for a payday loan, you may be charged a default fee of up to £15, and the missed payment will be reported to the credit reference agencies, which can affect your credit score. Thanks to the FCA price cap, the total you repay can never be more than double what you borrowed. Contact your lender as soon as possible if you’re struggling, as they must treat you fairly and consider options such as a reduced payment plan.
Is a direct lender regulated differently from a broker?
Both are regulated by the FCA, but for different activities. Direct lenders are authorised to lend money, while brokers are authorised to introduce customers to lenders. Both must follow the FCA’s rules on fair treatment, clear information and handling complaints.